There comes a time in many family-owned businesses and groups of small and medium-sized enterprises when the corporate structure no longer reflects the reality of the business. There are multiple companies, assets are scattered, profits are managed without a common strategy, and succession planning should be addressed before problems arise.
In this context, a holding company structure can help organize the group, segregate risks, optimize tax planning, and prepare for important decisions such as bringing in new partners, selling a subsidiary, or facilitating a generational transition.
In 30 seconds: the key points of this post
- A holding company is a parent company that brings together several subsidiaries under a common umbrella.
- Its advantages fall into three categories: business (organization and risk separation), tax (dividends, sale of shares, consolidation), and estate and inheritance (asset protection and generational succession).
- It is not an automatic way to save on taxes: it only adds value if it meets a real need of the group and is economically justified.
- If handled improperly, it can result in costs, obligations, and tax risks. A preliminary assessment is essential.
The key is to understand that a holding company is not an automatic way to save on taxes.
It is a tool for business, estate, and family planning that adds value only when it addresses a real need of the group.
In this article, we analyze the main advantages of a holding company structure, what practical implications it may have, and what precautions should be considered before reorganizing a company or family business.
What Is a Holding Company, and When Does It Make Sense for a Business Group?
A holding company is a parent company that owns one or more subsidiaries. The parent company centralizes ownership or strategic management of the group, while the subsidiaries continue to conduct their respective operations.
Simply put: a holding company allows you to transition from separate companies to a corporate structure organized under a single parent company.
It makes sense to establish one when there are circumstances that justify it: multiple business lines with different operating models, significant assets that need to be protected, profits that you want to reinvest, a succession plan that needs to be prepared before a problem arises, or a potential sale or the entry of new partners on the horizon.
“A holding company is not an automatic way to save on taxes. It is a tool for business, estate, and family planning that adds value only when it meets a real need of the group.”
In family-owned businesses, that preliminary analysis is especially important.
A holding company can help clarify the relationship between ownership, management, and the family—yes.
But it only adds value if it is designed with a clear commercial, tax, and asset-management rationale from the outset.
Key Advantages of a Holding Company Structure
The advantages of a holding company structure depend on how the group is organized and on the company’s objectives.
Even so, in family-owned businesses and corporate groups, they tend to appear in several very specific contexts.
The following table summarizes them as an initial map:
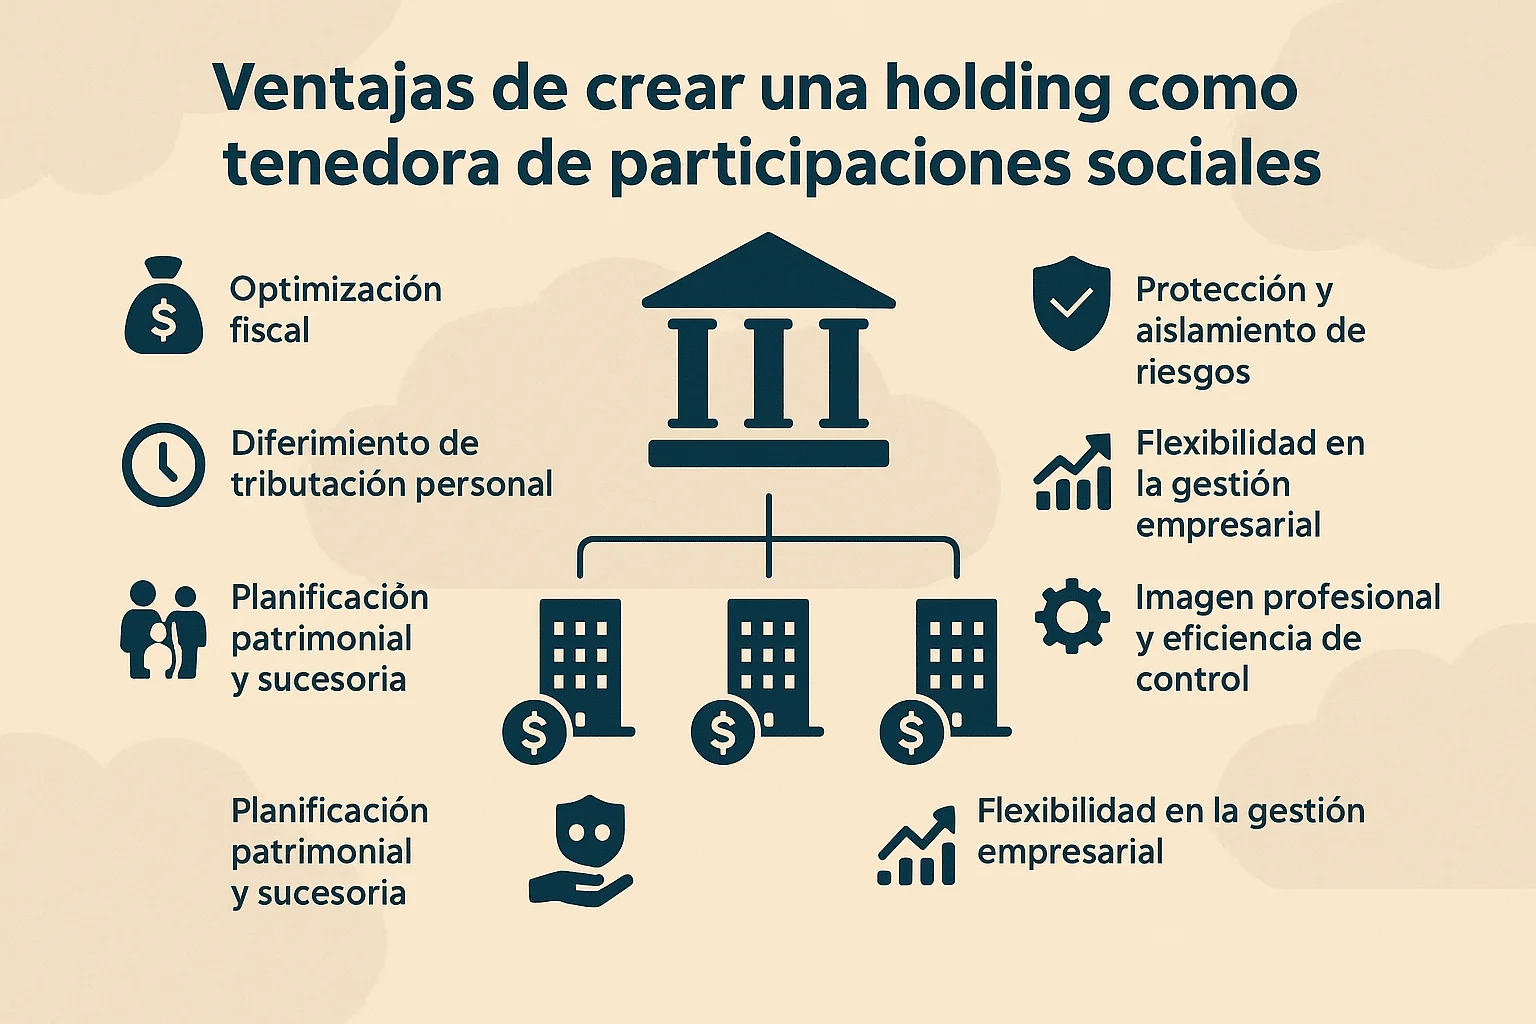
AdvantageSummaryCorporate StructureIt brings together several companies under a common parent company and provides a comprehensive overview of the group.Risk SegregationIt allows you to assign each activity, asset, or line of business to the most appropriate entity.Tax PlanningIt helps organize the group’s tax affairs, provided there is an economic rationale and the legal requirements are met.Reinvestment of ProfitsIt channels dividends to the parent company to finance projects, reduce debt, or drive new investments.Membership or Investor RegistrationIt allows you to restrict third-party access to a specific subsidiary without necessarily affecting the rest of the group.Sale of Subsidiaries or Business UnitsIt makes it easier to identify what is being transferred, what assets are included in the transaction, and what obligations remain with the group.Family SuccessionIt helps ensure a smoother transition of the group to the next generation.Asset ProtectionOrganize assets and investments in a more coherent manner that is less exposed to unnecessary risks.
Next, we’ll see why these advantages can be important when the group grows, acquires companies, or needs to make major decisions.
Business Advantages of a Holding Company
Before discussing taxes, the first question any group with multiple companies should ask itself is a simpler one: Does our structure reflect how the business actually operates?
In many cases, the answer is no.
And that has practical consequences that go beyond taxation.
Organize companies and business lines
When companies are formed out of necessity and without an overarching strategy, the result is often a group that is difficult to manage.
No one has a clear picture of what each company does, what role it plays within the group, or where the risks or value lie.
The holding company serves as the parent company and provides structure to this fragmented entity.
For a CEO, a CFO, or a family partner, that big-picture view has a very specific impact,
For example, it helps determine where to invest, which companies need financing, and what decisions need to be made from a global perspective.
Allocate risks across activities and assets
An operating company may have a concentration of employees, contracts, debt to suppliers, and liability to customers.
If that same company holds real estate, retained earnings, or strategic equity interests, the entire corporate assets are exposed to the same risks.
Under a holding company structure, companies can be organized by business activity, function, or type of asset.
That separation must be justified, but when properly implemented, it reduces exposure and prevents an operational problem from affecting assets that should not be at risk.
For groups with significant assets, this is often one of the strongest reasons to consider a reorganization.
Facilitate the entry of partners or investors
When a member, investor, or strategic partner joins, the structure must make it clear what their role is, what rights they will have, and what risks they assume.
With a holding company, that investment can be limited to a specific subsidiary linked to a particular line of business, without necessarily affecting the rest of the group.
This facilitates negotiations, protects the interests of the other companies, and allows for the drafting of more precise shareholder agreements.
Preparing to Sell a Company or Subsidiary
A sale often becomes complicated when the scope of the transaction is unclear.
If a business shares ownership with real estate, debt, contracts from other lines of business, or assets unrelated to the transaction, it may be necessary to restructure before negotiating. And that restructuring may come too late.
A holding company structure helps ensure that each business activity is organized into a separate entity.
This reduces uncertainty, facilitates due diligence, and makes it possible to move forward with a future transaction that has a clearer and more defensible structure.
That’s another reason to think about this before you need it.
Professionalizing the group’s management
As a group grows, informal management becomes less effective. Financing, investments, shared services, dividend policy, and growth planning begin to require common standards.
The holding company can serve as a hub for coordinating strategic decisions and managing the relationships among its subsidiaries.
In family-owned businesses, this point is particularly important, as it helps distinguish between ownership, management, and the family, and establishes a more stable structure for generational succession.
Ultimately, the business advantage of a holding company lies in creating an organization that is better equipped to grow, operate, and make important decisions.
Does your structure reflect how the business operates?
Organizing your group before a problem arises prevents you from having to rush to restructure it. We can help you determine whether a holding company is a good fit for your group.
Tax Benefits of a Holding Company
Many companies consider setting up a holding company for tax reasons. This makes sense, provided that the structure reflects an economic reality and complies with the applicable legal requirements.
The main advantage lies in shifting from company-by-company taxation to group-level planning.
This allows for better management of dividends, the reinvestment of profits, the sale of shares, tax consolidation, and family succession.
Intra-group dividends and reinvestment of profits
One of the most significant tax advantages is that the profits generated by a subsidiary can be transferred to the parent company in the form of dividends.
When the requirements for corporate income tax are met, those dividends may qualify for the double taxation exemption at the rate provided by law.
As a result, liquidity remains strong at the parent company and can be used for new investments, debt reduction, financing subsidiaries, or future corporate transactions.
The difference compared to direct distributions to individual partners is significant: the funds remain within the group and are managed according to a common business strategy.
“The funds remain within the group and are managed according to a common business approach.”
Sale of shares or subsidiaries by the parent company
Another tax benefit arises when the parent company sells shares in a subsidiary or another company within the group.
If the legal requirements are met, the income earned may qualify for the corresponding corporate income tax exemption.
This is useful in the case of partial sales, divestitures, the entry of new investors, or the transfer of a business line. The funds may remain with the parent company to be reinvested within the group or to finance new operations.
In this case, advance planning is key. It is necessary to review the length of time the interest has been held, the percentage owned, the composition of the transferred company, and the existence of exempt assets.
Tax Consolidation in Corporate Groups
In some groups, a holding company structure can facilitate the application of the tax consolidation regime for corporate income tax.
This system allows multiple companies to be taxed as a single tax unit when they meet the legal requirements. Thus, the group’s results are analyzed collectively rather than on a company-by-company basis.
It can be useful when one company is generating profits and another is in a phase of investment, expansion, or losses. In such cases, tax consolidation allows for the offsetting of results within the group and improves overall tax planning.
Family Business, Wealth Tax, and Inheritance
In family-owned businesses, a holding company can also help manage tax matters related to the Wealth Tax and the Inheritance and Gift Tax.
In the area of Estate Tax, equity interests in entities may be exempt if the legal requirements are met. To determine this, one must review the actual economic activity, percentage of ownership, management functions, compensation, and the composition of the estate. In the area of Inheritance and Gift Tax, consolidating equity interests under a parent company can facilitate a more orderly transfer within the family group.
There may also be significant tax breaks related to family-owned businesses.
This analysis is particularly important when there are real estate properties, excess cash, financial assets, or companies with different functions within the group.
Do you want to get your group’s tax affairs in order?
Intra-group dividends, the sale of equity interests, tax consolidation, or tax exemptions for family-owned businesses: each benefit requires meeting specific requirements and careful advance planning.
Asset and Estate Planning Benefits of a Family Holding Company
A family holding company also makes it possible to manage assets, property, succession, and family governance through a parent company.
Succession is not just a tax matter. It is a decision about how what has been built is passed on, who participates in decision-making, what role the next generation will play, and how the business remains unified when the interests of different family branches begin to diverge.
A family holding company allows you to address these issues before time or conflicts force you to do so.
“A family holding company allows you to address these issues before time or conflicts force you to.”
Protecting Business Assets
Separating operating activities from assets is meaningless if the separation is artificial. But when it is based on sound logic—one company assumes the business risks, while another holds the assets that need to be protected—that structure reduces exposure and prevents the entire corporate assets from depending on what happens in the operating company.
It’s not absolute protection. But it’s a system that, when well-designed, makes a difference in situations where it counts.
Organizing the Family Business
In a family business, the lack of structure blurs the line between business and personal matters. Conflicts among partners block business decisions. Business decisions lead to conflicts among family members. And at some point, no one is quite sure where one ends and the other begins.
The holding company can serve as the framework for structuring that relationship: who has what rights, how profits are distributed, who makes strategic decisions, and what happens when someone wants to leave.
A family protocol or a partners’ agreement is more robust when it is based on a clear corporate structure than when it attempts to function within a loosely organized group.
Planning for Business Succession
A holding company makes it possible to plan for the transfer of the group through a parent company, rather than managing scattered equity interests in various companies.
This helps define how the business unit will be managed, who will be involved in decision-making, and what role the next generation will play.
Succession brings order and reduces improvisation, especially when there are multiple heirs or family branches.
When Is It Worth Considering a Holding Company Structure?
A holding company is worthwhile when it helps meet a real need of the group.
The question shouldn’t be “Can we set up a holding company?” but rather “What business, tax, estate, or family issue do we want to address?”
It usually makes sense to study this structure in situations such as these:
- There are several companies with different operations, assets, or risks.
- Family-owned businesses need to prepare for generational succession.
- There are properties, reserves, or equity interests that should be organized within the group.
- The group wants to reinvest profits from some companies into others.
- The possibility of bringing in partners or investors for a specific line of business is being considered.
- There is a possibility of a future sale of a company, subsidiary, or business unit.
- The current structure has grown through accumulation and is beginning to raise concerns about control, risks, and taxation.
In all these cases, the decision must be based on a thorough preliminary analysis: which companies exist, what assets each one holds, how profits are distributed, what risks the group assumes, and what long-term objectives need to be protected.
Simple Example
A family-owned business has an operating company, a real estate company, and a third company for a new line of business. By consolidating them under a holding company, the family can channel dividends to the parent company, better segregate the risks associated with operations, and more systematically prepare for future succession, a partial sale, or the entry of new partners.
Risks of Setting Up a Holding Company Without Proper Planning
A poorly structured holding company can lead to unnecessary costs, obligations that are difficult to manage, and significant tax risks.
In practice, problems often arise when a reorganization is carried out too quickly or with an unclear purpose.
Some common risks include:
- Lack of a valid economic rationale. A structure created solely to obtain a tax advantage may be challenged by the tax authorities.
- Inadequately documented related-party transactions. Loans, services, leases, or transactions between companies must be properly justified and valued.
- Intragroup services without actual support. The parent company must be able to document which services it provides, to which companies, using what resources, and under what billing criteria.
- Issues related to VAT, withholding taxes, or invoicing. Certain internal transactions have tax implications that should be reviewed before they are carried out.
- Misallocated assets. Mixing real estate, cash, equity investments, or operating activities without a clear strategy can undermine asset protection.
- Excessive maintenance costs. More companies mean more accounting, tax, commercial, and administrative obligations.
- Conflicts among partners or family members. A new structure without clear rules can carry governance issues over to the parent company.
One of the most common mistakes is to start with the solution—creating a holding company—before identifying the problem.
“One of the most common mistakes is to start with the solution—creating a holding company—before diagnosing the problem.”
The order should be the opposite. Review the current structure, identify risks, define objectives, and only then decide whether a holding company is the right tool.
When It’s Not Worth It to Set Up a Holding Company
Creating a holding company makes sense when it provides structure, protection, or real efficiency. In simple structures, the cost and complexity may outweigh the benefits.
The following table summarizes when it is usually worth studying the structure and when, on the other hand, it may not be worth the effort:
It’s usually worth studying if…It might not be worth it if…There are several companies with different operations, assets, or risks.There is only one business activity, with no additional companies and no plans for growth.There are significant assets or property that should be organized and protected.The company’s assets are limited or consist of no significant assets to be organized.We need to prepare for succession, the admission of new partners, or the sale of a subsidiary.There are no plans for succession, bringing in new partners, a sale, or expansion.The tax, business, or financial benefits outweigh the maintenance costs.Maintenance costs exceed the expected profit, or the decision is made out of imitation.
In these situations, it is often more helpful to start with simpler solutions, such as reviewing articles of incorporation, organizing contracts, updating partnership agreements, or drafting a family protocol.
How Carrillo Can Help You
At Carrillo, we don’t start by asking, “How do we set up a holding company?” but rather by asking a more fundamental question: whether a holding company structure makes sense for your business.
Before recommending a reorganization, we analyze the group’s structure, where the assets are located, which companies assume risks, how profits are distributed, and what business, tax, estate, or family objectives underlie the decision.
Based on that assessment, we can help you evaluate the available options, design the most appropriate structure, and review the critical issues before making any decisions.
This analysis is important because a holding company offers significant advantages, but it can also entail costs, obligations, and risks if it is structured without a clear rationale.
In short: the goal is not to add complexity, but to design a structure that helps organize the group, better protect its assets, and make decisions with greater legal and tax certainty.
Do you own multiple companies, or are you considering reorganizing your family business?
We can help you review your current situation and decide on the best course of action, assessing whether a holding company structure would bring order, protection, and real efficiency to your group.
Frequently Asked Questions About the Benefits of a Holding Company Structure
Here are some of the most common questions that arise when assessing whether a holding company structure is a good fit for a business or family group.
What are the main advantages of a holding company structure?
The main advantages are typically related to corporate structure, risk segregation, tax planning, profit reinvestment, the entry of new partners, the sale of subsidiaries, and family succession. The actual benefits depend on each group’s specific situation: the number of companies, the type of assets, risks, family objectives, and growth plans.
What are the tax advantages of a holding company?
A holding company can facilitate the group’s tax management in several ways. In the case of intragroup dividends, a subsidiary’s profits can be transferred to the parent company, and—if legal requirements are met—the double taxation exemption can be applied at the corresponding rate. This allows liquidity to be concentrated at the group’s parent company for reinvestment, financing new activities, or reducing debt. It can also offer advantages when selling equity interests or subsidiaries, as the parent company can manage the transaction and better plan the allocation of the proceeds. Furthermore, in certain groups, tax consolidation may be considered, and in family-owned businesses, the connection to estate, inheritance, and gift taxes should be evaluated.
Does a holding company help you pay less in taxes?
A holding company should not be viewed as an automatic way to pay less tax. Its value lies in organizing the group’s tax affairs, facilitating the reinvestment of profits, and enabling certain transactions to be carried out with greater certainty. Any potential tax savings or efficiency will depend on the structure’s design, the economic rationale, and compliance with legal requirements.
When does it make sense to set up a family holding company?
It makes sense to consider this when a family business has multiple companies, significant assets, profits that the owners wish to reinvest, a succession plan that needs to be developed, or the possibility of bringing in partners or selling a portion of the business. It can also be useful when the current structure has grown through accumulation and is beginning to raise concerns about control, risks, taxation, or family continuity.
Does a holding company protect a business’s assets?
A holding company can help better organize assets and separate activities with different levels of risk. This protection requires a genuine and coherent structure. The separation of companies should not be done artificially, nor does it guarantee absolute protection, but it can help prevent the entire corporate estate from depending on a single operating company.
What are the risks of creating a holding company structure without proper planning?
The most common risks include a lack of a valid economic rationale, poorly documented related-party transactions, intragroup services without a real basis, VAT or withholding tax issues, misallocated assets, and unnecessary maintenance costs. Family or corporate conflicts may also arise if the parent company is established without clear governance rules.
When is it not worth setting up a holding company?
It may not be worthwhile when there is a single, simple business activity, limited business assets, no growth or succession plans, and maintenance costs that exceed the expected profit. In such cases, it may be more useful to put in order the articles of incorporation, contracts, shareholder agreements, or family agreements before forming a new parent company.
Is a holding company useful for small and medium-sized businesses, or only for large corporations?
A holding company structure is not exclusive to large multinationals. It can also be useful for small and medium-sized businesses and family-owned companies with multiple subsidiaries, significant assets, or planning needs. The key is that there must be a business, tax, estate, or succession-related reason that justifies the structure. When such a reason exists, it is worth analyzing it thoroughly and with the appropriate advice before making important corporate decisions.
Glossary: Key Concepts of a Holding Company Structure
- Holding Company: a parent company that holds an interest in one or more subsidiaries. The parent company centralizes ownership or strategic management of the group, while the subsidiaries continue to conduct their respective operations.
- Double taxation relief: a corporate income tax mechanism that prevents the same profit from being taxed twice when it is distributed as a dividend among group companies, provided that the legal requirements are met.
- Tax consolidation: a corporate income tax regime that allows multiple companies within a group to be taxed as a single tax unit, with income analyzed on a consolidated basis rather than on a company-by-company basis.
- Valid economic reason: a genuine business rationale that justifies a corporate reorganization beyond mere tax benefits, which is required so that the tax authorities do not challenge the transaction.
Regulatory References
Official and current regulations that form the basis for the tax, asset, and estate planning analysis of a holding company structure.
- Law 27/2014 on Corporate Income Tax. It regulates corporate taxation, the exemption from double taxation on dividends and income from equity interests (Art. 21), and the tax consolidation regime for corporate groups.
- Article 21 of the Income Tax Law (LIS). This article governs the exemption for dividends and for capital gains arising from the transfer of equity interests, subject to the legally established requirements. It forms the basis for the tax treatment of intragroup dividends and the sale of subsidiaries by the parent company.
- Law 19/1991 on the Wealth Tax. Among other things, it regulates the exemption of equity interests in entities when the requirements regarding economic activity, ownership, and management functions are met. This is relevant to family-owned holding companies.
- Law 29/1987 on Inheritance and Gift Tax. It regulates the tax breaks applicable to the transfer of family businesses and equity interests, which are key to the group’s succession planning.
The content has been reviewed in accordance with the tax and commercial regulations in effect as of the date of this update. This article is for informational purposes only and does not constitute personalized advice. It will be revised when there are significant changes regarding corporate income tax, net worth tax, inheritance and gift tax, or the family business regime.